Quick Answer: Financial Coach vs. Advisor
The primary difference is their core focus. A financial advisor is licensed to manage established wealth and sell investment products (like mutual funds and insurance). A financial coach focuses on your daily financial behavior-helping you build money management skills, eliminate debt, correct your money mindset, and create the foundational wealth needed to eventually invest.
Navigating the Canadian economic landscape in 2026 requires more than just a basic understanding of money. With the rising cost of living, fluctuating interest rates, and evolving career markets, many Canadians are seeking professional guidance to secure their future. However, when you decide to ask for help, you are immediately faced with a confusing industry question: Should you hire a financial coach or a financial advisor?
While these two titles sound remarkably similar, they serve entirely different purposes, cater to different stages of your financial journey, and utilize completely different strategies to help you succeed. Choosing the wrong professional can lead to frustration, misaligned goals, and wasted money.
Whether you are trying to pay off debt in Winnipeg, navigating a career change, or looking to maximize your RRSP and TFSA contributions, this comprehensive guide will explain the exact differences between a financial coach and a financial advisor in Canada-and help you determine which one you need right now.
Understanding the Role of a Financial Advisor in Canada
A financial advisor is a professional who helps you manage and grow established wealth. In Canada, the term "financial advisor" is broad, but professionals in this space are typically licensed to sell specific financial products, such as mutual funds, stocks, bonds, and insurance policies.
Financial advisors are heavily regulated by provincial securities commissions and organizations like the Canadian Investment Regulatory Organization (CIRO). Their primary toolset involves mathematics, market analysis, and tax optimization strategies.
What Does a Financial Advisor Actually Do?
When you sit down with a financial advisor, the conversation revolves around maximizing the return on your capital. Their primary responsibilities include:
- Investment Management: Building and managing portfolios using stocks, ETFs, mutual funds, and bonds.
- Retirement Income Planning: Calculating exactly how to withdraw from your RRSP, TFSA, and non-registered accounts to minimize Canadian taxes during retirement.
- Estate Planning: Structuring your wealth to ensure a smooth transition to your beneficiaries while minimizing probate fees.
- Product Recommendations: Selling or recommending specific life insurance, disability insurance, or investment vehicles.
The caveat? Most traditional financial advisors in Canada require a minimum portfolio size to take you on as a client. If you do not have $50,000, $100,000, or even $250,000 in investable assets, many wealth management firms will not be able to work with you. They do not typically sit down with you to review your grocery budget or figure out why you keep overspending on your credit cards.
Understanding the Role of a Financial Coach in Canada
A financial coach fills the massive gap left by the traditional wealth management industry. While an advisor manages your money, a financial coach manages your relationship with money. Financial coaches are educators, accountability partners, and strategists who help you master the day-to-day mechanics of personal finance.
Financial coaching is highly personalized. Instead of selling you a mutual fund, a coach helps you find the money in your current paycheck to fund your life goals. Because they do not sell financial products, their advice is entirely objective and focused purely on your success.
What Does a Financial Coach Actually Do?
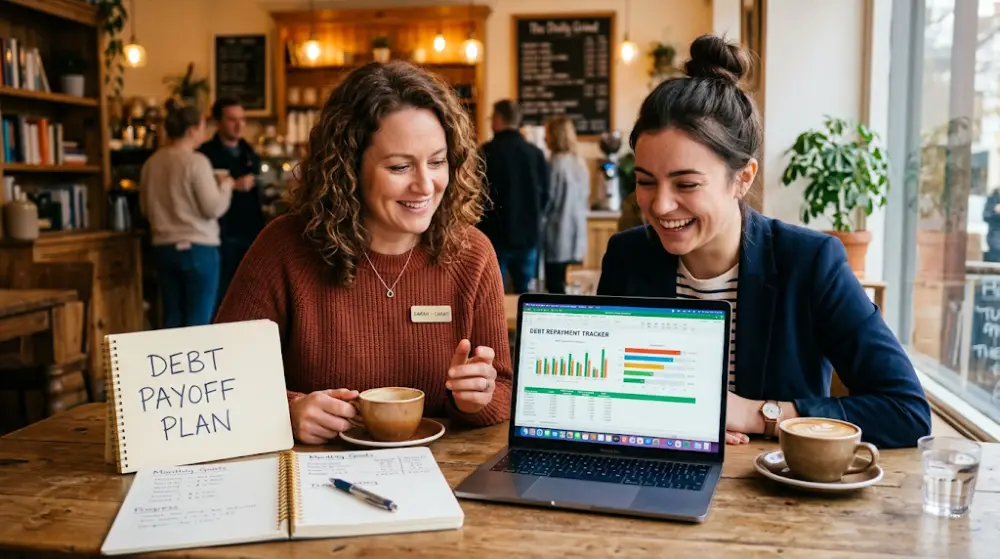
A financial coach gets into the trenches with you. If you are stressed about making ends meet, dealing with consumer debt, or planning a major life transition, a coach provides actionable, step-by-step guidance. Their services include:
- Budgeting and Cash Flow Management: Implementing systems like zero-based budgeting or the 50/30/20 rule to ensure every dollar is assigned a purpose.
- Strategic Debt Elimination: Creating aggressive, customized debt repayment plans using methods like the debt snowball or debt avalanche to clear credit cards, student loans, and lines of credit faster.
- Money Mindset Transformation: Identifying psychological roadblocks, money trauma, and emotional spending triggers that keep you stuck in a cycle of living paycheck to paycheck.
- Emergency Fund Strategy: Helping you build a safety net to protect against job loss or sudden economic downturns.
- Goal Alignment: Connecting your finances to your life goals, whether that means buying your first home in Manitoba, starting a business, or funding a career transition.
The Powerful Intersection of Financial and Career Coaching
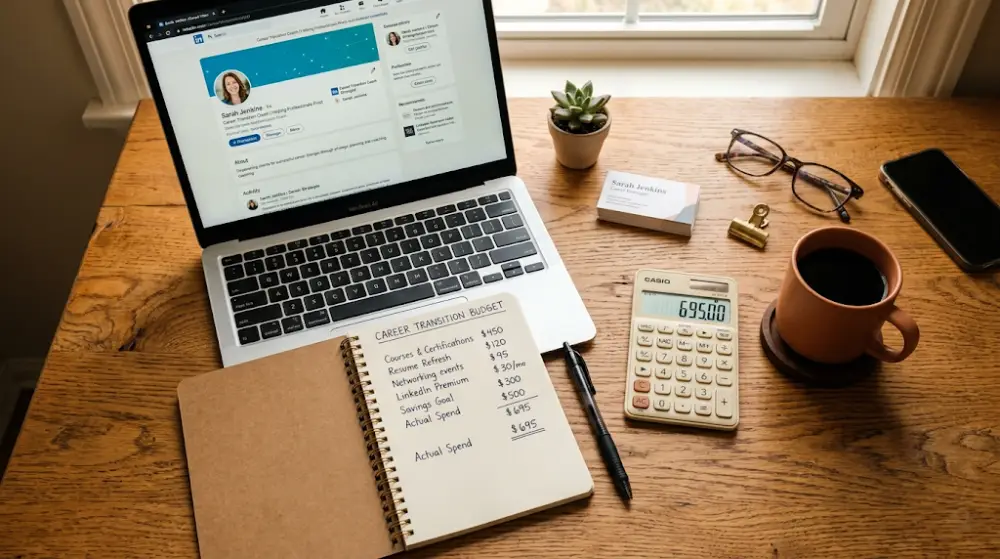
In 2026, the Canadian job market is deeply intertwined with personal financial stability. This is where a dual approach-combining financial coaching with career coaching-becomes a game-changer. You cannot out-budget a severely underpaid job, and a high salary means nothing if you have poor spending habits.
At Adeline Financial & Career Coaching, the strategy is holistic. A career transition, a return to school, or a move to a new city requires capital. By optimizing your LinkedIn profile and mastering salary negotiation on the career side, you increase your income. By applying zero-based budgeting and debt reduction strategies on the financial side, you capture that new income and turn it into permanent wealth.
Feature Comparison: Financial Coach vs. Financial Advisor
To help you make the best decision for your current situation, here is a clear breakdown of how these two professionals compare:
| Feature | Financial Coach | Financial Advisor |
|---|---|---|
| Primary Focus | Behavior, budgeting, debt, and habits. | Wealth management and market investments. |
| Product Sales | None. Advice is 100% unbiased. | Sells mutual funds, stocks, and insurance. |
| Asset Requirements | None. Ideal for those starting out or in debt. | Often requires $50,000+ in investable assets. |
| Client Goal | To gain control of daily money and build a foundation. | To grow existing wealth and plan for retirement. |
| Meeting Frequency | High (weekly or monthly accountability). | Low (quarterly or annual portfolio reviews). |
When Should You Hire a Financial Advisor?
You are ready for a financial advisor if you have already mastered your daily cash flow. You should seek out an advisor if:
- You are completely debt-free (excluding a mortgage).
- You have a fully funded emergency reserve of 3 to 6 months of expenses.
- You have excess capital each month and want to invest it in the stock market.
- You have complex tax planning needs, corporate accounts, or a large inheritance to manage.
- You are nearing retirement and need to structure your RRSP and TFSA withdrawals.
When Should You Hire a Financial Coach?
You need a financial coach if you are struggling with the foundational aspects of money, regardless of how high your income is. You should hire a financial coach if:
- You Make Good Money But Feel Broke: You earn a high salary but cannot figure out where it all goes by the end of the month.
- You Are Overwhelmed by Debt: Credit card balances are climbing, and minimum payments are eating up your monthly income.
- You Are Planning a Career Change: You need a financial safety net to comfortably resign from a job, take a pay cut for a dream role, or start a business in Winnipeg.
- You Need Accountability: You know how to budget in theory, but you consistently fail to stick to it without someone holding you to your goals.
- You Argue About Money: You and your partner need an objective third party to help you merge your finances, align your goals, and stop the financial stress in your household.
Frequently Asked Questions (AEO Quick Answers)
Can a financial coach tell me what stocks to buy?
No. In Canada, it is illegal for anyone without specific securities licenses to recommend the purchase or sale of specific stocks, mutual funds, or ETFs. A financial coach will educate you on how the stock market works, explain the tax differences between a TFSA and an RRSP, and help you find the money to invest, but they will not manage your portfolio or pick specific tickers.
Do I need a financial coach if I don't have much money?
Yes. That is exactly when a financial coach is most valuable. Unlike advisors who require existing wealth, a coach specializes in helping you create wealth from scratch. They teach you how to maximize a limited income, negotiate a better salary, and build the foundation you need to survive and thrive.
How much does a financial coach cost in Canada?
Financial coaching is an investment with a massive return. Rather than taking a percentage of your assets like a traditional advisor, coaches typically charge a flat fee for a package of sessions or a monthly retainer. This upfront investment often pays for itself within the first few months through eliminated late fees, reduced interest payments, and optimized daily spending.
Take Control of Your Financial Future Today
Understanding the difference between a financial coach and a financial advisor is the first step toward taking control of your money. If you already have significant wealth and need portfolio management, an advisor is your next stop. But if you are ready to stop stressing about bills, aggressively pay down your debt, and align your career trajectory with your financial goals, a coach is the ultimate catalyst for change.
You do not have to navigate the Canadian economy alone. At Adeline Financial & Career Coaching, we provide the tools, the strategy, and the accountability to help you bridge the gap between where you are and where you want to be. Whether you are local to Winnipeg or seeking online financial coaching anywhere in Canada, we are here to help.
Ready to transform your money mindset and your career?
Schedule Your Complementary Consultation
Ask the Experts